EN | CN
All you need to know about transfer pricing documentation.
Singapore's latest transfer pricing guidance brings welcome clarity on share-based compensation in intercompany service fees. Discover what has changed, the opportunities available for earlier years, and why businesses should review their arrangements before key deadlines.
Transfer pricing season is here. From new guidance on related party transactions to enhanced focus on loans and documentation, learn the key updates, common pitfalls, and practical questions every Singapore business should be asking before year-end.
On 30 July 2026, the Inland Revenue Board of Malaysia (IRBM) released its new Malaysia Transfer Pricing Guidelines on Controlled Financial Transactions: Intra-Group Loans (MFTIL). The guidance provides a comprehensive framework for assessing, pricing and documenting intra-group loans under Malaysia’s transfer pricing regime.
Adriana Calderon shares her perspective on the evolving tax landscape and the role of collaboration at the SCTP Singapore Tax Congress.
The Inland Revenue Authority of Singapore (IRAS) has updated its Frequently Asked Questions relating to the Reporting of Related Party Transactions (RPT Form), providing additional clarification on the scope of entities and individuals that may be regarded as related parties for reporting purposes.
On 1 June 2026, the OECD released a public consultation draft revising Chapter VII of the OECD Transfer Pricing Guidelines – the chapter dealing with intra-group services. The draft is extensive but does not change the underlying arm’s length principles.
The Inland Revenue Authority of Singapore (IRAS) released the 9th Edition of the Singapore Transfer Pricing Guidelines (TPG) on 4 June 2026. The update introduces targeted clarification on the treatment of share‑based compensation (SBC) in the context of intercompany services arrangements remunerated on a cost‑plus basis.
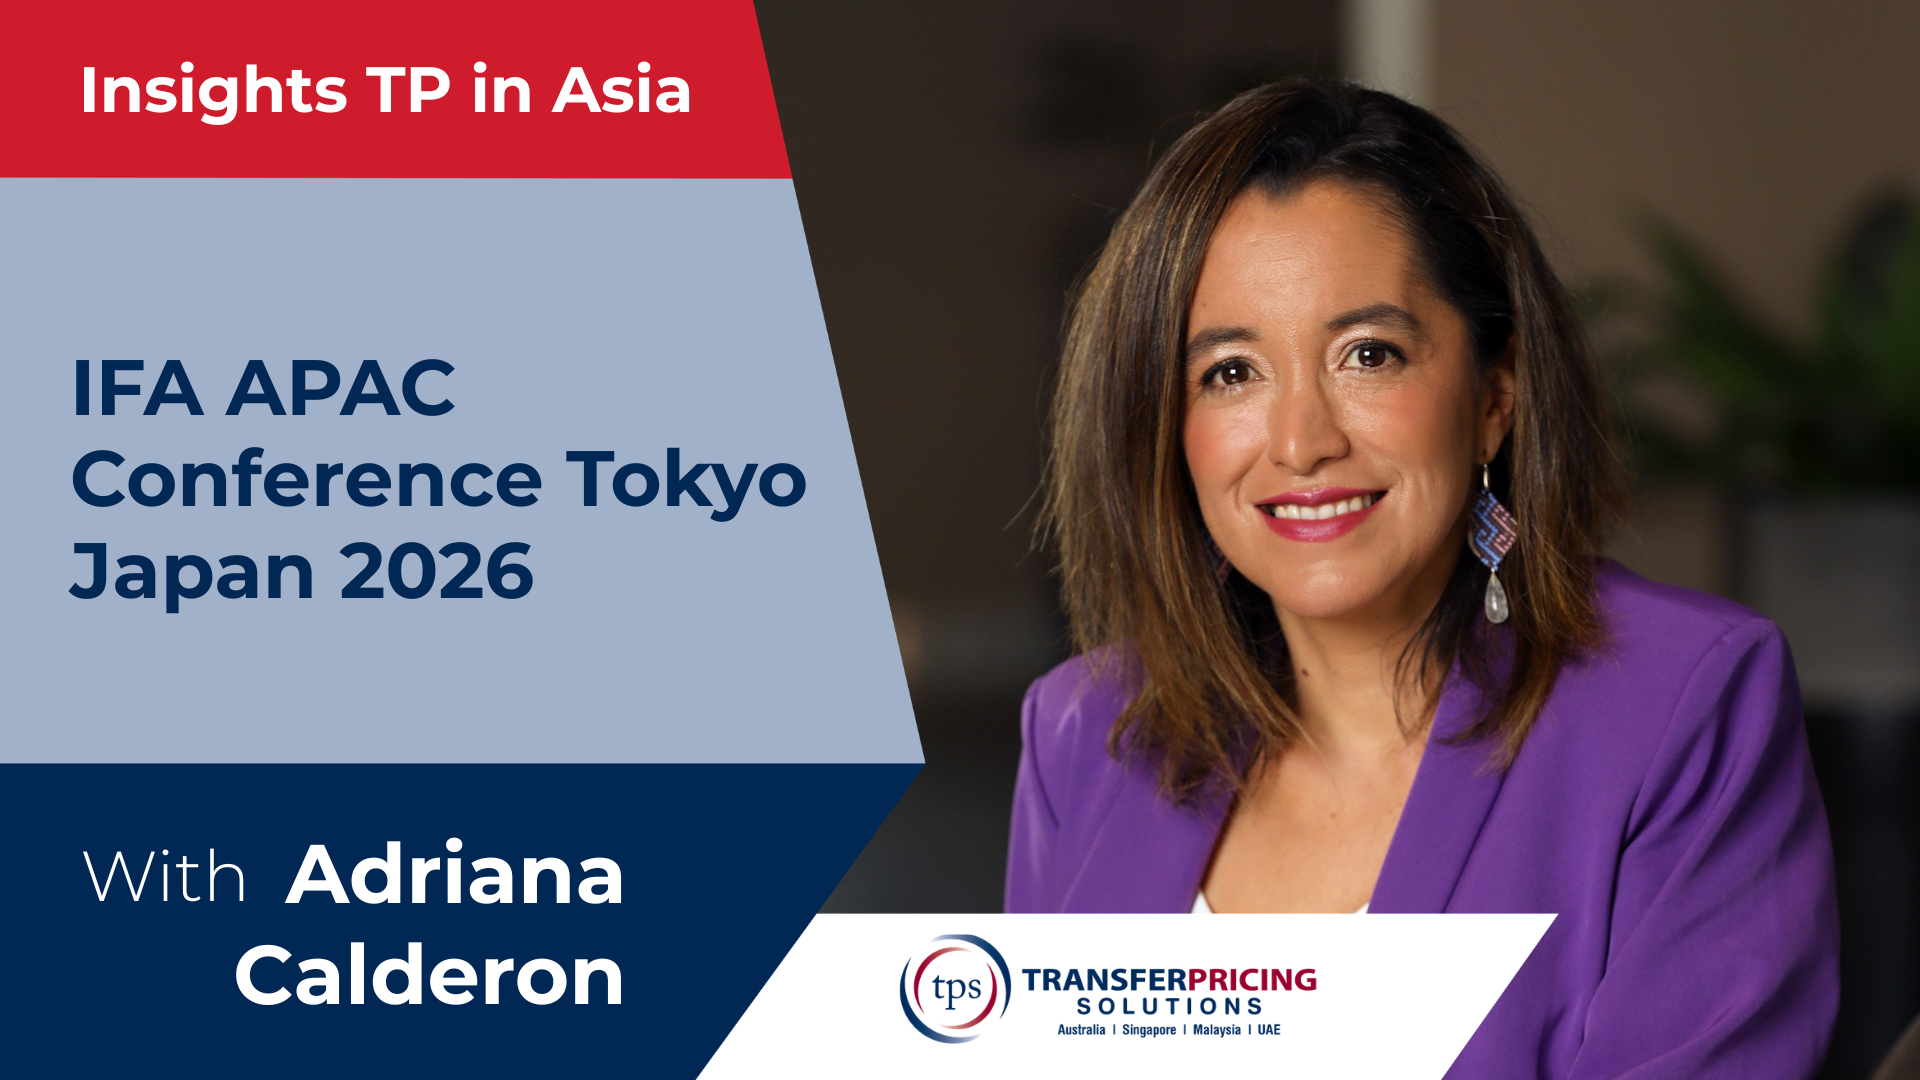
Adriana Calderon, Managing Partner - Asia & Malaysia at Transfer Pricing Solutions, shares insights from the IFA APAC Conference in Tokyo, highlighting key trends in transfer pricing across Asia. She explores regional differences in approach, increasing regulatory complexity, and rising audit activity, while reflecting on the importance of global networks in fostering collaboration and shaping the future of international tax.
Malaysia’s transfer pricing framework continues to evolve, with the Inland Revenue Board of Malaysia applying increasing scrutiny to how multinational groups price, document and defend related‑party transactions. For businesses operating in Malaysia, transfer pricing has become a core tax risk area rather than a routine compliance exercise.
Across Asia, transfer pricing audits are becoming more frequent, more detailed and more analytically driven. Tax authorities are no longer limiting their reviews to whether documentation exists. Instead, they are interrogating whether transfer pricing outcomes genuinely align with commercial reality, operational substance and financial results over time.
As tariff wars intensify, government deficits balloon, and supply chains fragment, the OECD’s 15% global minimum tax has shifted from a technical compliance issue to a strategic imperative reshaping how and where multinational enterprises compete.